Thursday, October 20, 2016

When Rams Ram

When Robert came into the office and showed us the pictures of a herd of rams running in front of his car, I thought it was the perfect time to make sure everyone knows what happens if a ram decides to ram your vehicle. It's also important to know the difference in coverage between a ram ramming your car and your car ramming a ram (there is a difference)!

When a RAM decides to ram you: If a ram decides to challenge your car to a battle, you can expect your insurance company to cover the claim under your comprehensive - other than collision - coverage. Even though, technically, the ram collided with your car, it should be considered a comprehensive claim because you did not collide with the ram. The distinction between the two is important because, for the most part, a comprehensive claim will NOT raise your insurance premiums but a collision claim will!

Comprehensive claims are for things that happen TO your vehicle but not as a result of your driving. Hail, wind, vandalism, theft and a ram ramming your vehicle are all examples of comprehensive claims. Because things that happen TO your car are usually no fault of your own, most insurance companies do not count a comprehensive claim against you and do not raise your insurance rates. Unless you have comprehensive coverage on your vehicle, you will be on your own to cover the cost to fix any damage from your car from these types of events.

Comprehensive coverage is usually required by your lender if you have a loan on your car, and the insurance company will give you a comprehensive deductible (typically $500-$1000) that you are responsible for paying if you file a comprehensive claim. If you own your vehicle outright you may choose to remove the comprehensive coverage in order to lower your insurance premiums but, you'll be solely responsible for the damages if your vehicle is damaged.

When YOU ram a ram: Chances are, if you ram a ram, it will be on accident and not on purpose. However, if you (your vehicle) runs into a ram, most insurance companies will consider that to be a collision claim because your vehicle collided with the ram. Collision claims ARE typically counted against you if the collision is considered to be your fault. So, if you are sitting at a stop light and someone rear ends you, the collision would not be your fault and your insurance rates should not be affected.

However, if a ram runs across the road and you collide with it, most insurance companies will consider that to be an at-fault collision and increase your rates. You may be asking why it would be considered your fault if the ram ran out in front of you? Because you are expected to be in control of your vehicle and avoid objects in the road. Sometimes your only option is to hit the ram instead of running into another vehicle or driving off the road. It happens, but it is still considered an at-fault collision because you collided with the ram.

In Colorado, a deer is about the only animal that you can collide with and have it count as a comprehensive claim instead of a collision claim. Dogs, horses, rams, etc. usually fall under the collision coverage of your insurance policy. Of course, you must purchase collision coverage for your vehicle in order for your insurance company to pay a claim. On the flip-side, if there were no other vehicles involved and no tickets issued, you may choose to pay for the damage of colliding with a ram out of your own pocket in order to keep your insurance company out of it and avoid having your insurance premiums go up.

It can get a little confusing, I know. The easiest thing to do if you find your vehicle in a confrontation with a ram is to call your local, professional agent and ask for advice. Every situation is different and it's important to have a pro to discuss your situation with.

Tuesday, April 12, 2016

Does My Home Need Flood Insurance?

If you’ve lived in Colorado for very long, you know that with the warmer temperatures and summer season, we get a lot of rain as well. In fact, sometimes we get monsoons! Depending on where you live in El Paso county, you may find a lot of water making its way toward your home over the next 4-6 months. If you’re worried that some (or a lot) of that water may find its way into your home, you may want to consider flood insurance. Here’s what you need to know:
Your home insurance probably will not cover any type of flood damage. To be clear, a flood is NOT water that comes from inside of your home from a broken pipe or leaky dishwasher. A flood is from external, natural running water that enters your home, either from rainfall, standing or running water or even from underground.

Home insurance typically excludes flood damage to both your home and your belongings. Occasionally, there could be some coverage provided if the actual flood damage was preceded by another event that allowed the flood damage to happen. For example, if wind blew out your windows, allowing the rain to enter your home or (with some companies) if your sump pump fails and allows water to enter through your basement, there MAY be coverage. However, coverage for flood damage under your normal home insurance is rare and should not be relied on.
Insurance companies typically provide flood insurance through the National Flood Insurance Program. In 1968, Congress created the National Flood Insurance Program (NFIP) to help provide a means for property owners to financially protect themselves. The NFIP offers flood insurance to homeowners, renters, and business owners if their community participates in the NFIP. Participating communities agree to adopt and enforce ordinances that meet or exceed FEMA requirements to reduce the risk of flooding. El Paso county and most of Colorado participate in the NFIP.

Does the National Flood Insurance Program cover everything that happens to my home and belongings if it is flooded? Unfortunately, not, but it does cover a lot. For homes that do NOT have a basement, most of your home and contents should all be protected by your flood insurance policy (up to the coverage limits that you purchase). However, things work differently if your home DOES have a basement. Here is what is and isn’t covered, according to the NFIP:
“Flood insurance covers your home's foundation elements and equipment that's necessary to support the structure (for example: furnace, water heaters, circuit breakers, etc.). It's important to note that some items in your basement are covered under building coverage (like a furnace, hot water heater and circuit breaker) and others are covered under contents coverage that must be purchased in addition to building coverage (for example, your washer and dryer, or your freezer and the food in it). The NFIP encourages people to purchase both building and contents coverage. Flood insurance does not cover basement improvements, such as finished walls, floors, ceilings or personal belongings that may be kept in a basement.”

Is flood insurance expensive? It depends. If your property is not in an actual flood zone, it would qualify for a Preferred Risk Policy. Preferred Risk Policies cover everything that a regular policy covers but at a substantial discount. Most homes in El Paso county (but not all) qualify for a Preferred Risk Policy. Depending on your coverage choices, a Preferred Risk Policy will cost between $130 - $460 per year.
If, however, your home lies within a flood zone, flood insurance prices will vary dramatically. There are 26 different flood zone levels, each with its own insurance rates. The higher the flood zone, the more likely the property is to experience a flood and the more expensive the flood insurance will be.

Can I start my flood insurance right before a storm starts? Unless you are required to have flood insurance for a home loan closing, there is a 30 day waiting period before coverage begins on flood insurance policies. The time to buy your flood insurance and get the coverage for your property is 30 days (or more) before the rain clouds gather above your home!

To find out if you’re property is in a flood zone or to get a flood insurance proposal, contact our office at 719-685-8585 and we’ll be happy to help.

Thursday, January 7, 2016

Doing What You Don't Want Today So You Can Do What You Do Want Tomorrow

My brother (Robert) went in for his annual skin check today - something he hates doing. Unlike me, he's always been prone to sunburns and, now that he's getting a little older, skin cancer (or pre-cancer, at least). The reason he hates going in for his annual check is because he almost always has to have pre-cancerous spots either frozen or cut off. He comes back to the office with a few bandages and a few red spots and then, for the next few weeks, he has to deal with people asking him about the red spots on his face while he's healing.

But as much as he dislikes getting poked, prodded, frozen and cut, he does it anyway because he knows it will help him do something he does want to do in the future - live a long, cancer free life! He knows he needs to be vigilant with his annual checks and consistent about removing spots that could turn into something worse if not dealt with early.

It would be easier for him to ignore the warning signs, skip the doctor and avoid getting poked and prodded, but he knows that if he only thinks about what he wants today, a time will come where it will be too late to take care of his tomorrows. He knows that putting things off may be easier and feel a little better today but it will only make things harder to fix in the future (or maybe impossible).

The same rules apply to retirement plans and preparing for the future. While it is far easier to put off saving and thinking about retirement in order to buy an extra latte or go out a few more times a month, the longer you put it off, the harder it is to catch up on your savings in the future. However, the sooner you start doing what you don't want to do (skipping a latte in order to fund an IRA, for example), the easier it is to do what you want later in life (like retiring with a bunch of money).

Saving for retirement is one of those things that is easy to put off because retirement seems so far away. But when it comes to the amount of money you have waiting for you in retirement, the amount of time you have can either be your best friend or your worst enemy. One of the keys to having boatloads of money in retirement is giving your money plenty of time to grow. Here's an example from Business Insider magazine that shows the difference of starting earlier vs. starting 10 years later:

"Consider two hypothetical savers, Emily and Dave. Emily puts $200 per month into a retirement account with an estimated 6% rate of return starting at 25. Dave starts saving $200 per month at 35, just 10 years after Emily. Both continue to add $200 each month until they retire at 65.

By the time they are 65, Emily has contributed $96,000, while Dave has contributed $72,000.
Here's the trajectory of both of those accounts:

Emily started saving just 10 years earlier and put in only about 33% more money into her account than Dave put in his. But by the time they are both ready to retire, Emily has almost twice as much as Dave — Emily has $402,492, and Dave has $203,118. That extra 10 years of compounding returns has made Emily's situation far better than Dave's when they are 65."

The moral of the story and the example from Business Insider is simple, the earlier you start, the better off you are. If you think it's too late for you because you didn't start early enough, you'll still be better off in retirement if you start saving today than if you beat yourself up about it for the next year or two before finally starting!

If you don't know where to start or what to do, call the office and make an appointment to come in for a visit. We've got a Chartered Financial Consultant in the office that can help answer questions and lay things out for you in a way that's simple and easy to understand. And if you come in within the next few weeks, pay no attention to the red spots on his forehead!

Tuesday, August 27, 2013

Is That Considered A Flood?

With all of the heavy, heavy rains we've been getting across the city of Colorado Springs and surrounding areas (and the flooding that's been coming along with it), it seems like a good idea to make sure you know what is and is not considered a flood as well as what is and is not covered under most home insurance policies when it comes to flood damage.

First, what is considered a flood? The dictionary defines "flood" as a rising and overflowing of a body of water onto normally dry land. For insurance purposes however, the word "rising" is the key to distinguishing flood damage from water damage. Generally, damage caused by natural flowing water that comes from the sky OR water that has been on the ground at some point before damaging your home is considered to be flood damage. A handful of examples of flood damage include:
  1. A nearby river overflows its banks and washes into your home
  2. A heavy rain seeps into your basement because the soil can't absorb the water quickly enough
  3. A heavy rain or flash flood causes the hill behind your house to collapse into a mud slide that oozes into your home
  4. Your home is located at the bottom of a hill or in an area that water runs through, filling your window wells and damaging your basement
Photo examples of what insurance considers to be a flood include:


The above pictures are from a recent storm here in Colorado Springs and any damage caused by the running water and heavy rain would NOT be covered under your home insurance policy. The last photo was from the same storm, but left a few feet of hail instead of running water. However, for insurance purposes it could still be considered flooding if the hail filled up your window wells and then melted and seeped into your basement, causing damage. In order to be covered for these types of events, you must carry flood insurance.
 
Flood insurance can be obtained through your local agent, but it is a separate policy from your home insurance and, very important to note, has a 30 day waiting period for coverage to begin UNLESS the policy is required for a loan closing.
 
The good news about flood insurance is that it is relatively inexpensive if you are not in a flood zone, ranging from $129 - $458 per year for a home owner, depending on the amount of coverage you need and whether or not you have a basement.
 
If you live near a burn area, there is an increased likelihood of water runoff and water damage because the ground is not able to absorb the rainfall and you may need to consider a flood insurance policy as an extra layer of protection for your home. If your home is located in an area that has a lot of runoff passing through your yard or if you are near a gully or stream, you too may want to purchase a small flood insurance policy for the peace of mind of knowing you would have some assistance if the waters get high again.
 
To talk about your particular home and situation and find out if you need this additional coverage, contact your local, professional insurance advisor who understands the unique risks that Colorado Springs, Manitou Springs and surrounding areas are facing right now. Hopefully you'll never be impacted by flood waters, but if you are, it's important to know that you have the right kind of coverage to protect your home and personal property.

Monday, July 8, 2013

What the bottom of the Grand Canyon taught me about investing for retirement. Part 1

My dad and I have been talking about rafting through the Grand Canyon for years. In June, we finally
had the opportunity to spend seven days (along with my son, Christian) traveling 188 miles down the Colorado River through the heart of the canyon. WOW, what an adventure! Rapids, waterfalls, slot canyons, hikes, camping...it was 7 full days of pure amazement. On top of all of the fun we had (including two opportunities to do some cliff jumping - check out the photos on Facebook.com/MyInsuranceGuys) I was also reminded of quite a few lessons that relate back to the world outside of the canyon. Specifically, some do's and dont's for retirement planning.

The Grand Canyon is a world of extremes. The air temperature was 105º but the water temperature
was only 47º. One minute you’d be hot as could be begging for a rapid while the next minute you were freezing your butt off and begging for the sun. However, if you averaged the temperatures out and sat in the sun while you were soaking wet, it felt pretty darn good because you were in “the sweet spot”. Not too hot and not too cold, but right in the middle. You should look for that “sweet spot” in your retirement accounts too. You may be tempted to swing for the fences with your retirement investments in order to catch a big return, but more often than not you catch not only a part of a big upswing, but also part of a big downswing as well. Over time, investment portfolios with real big swings up and down always perform worse than those with a nice, consistent average in the sweet spot. Try to find the middle ground and build a portfolio that avoids the extremes. Not only do you typically get better results, you’re usually a lot more comfortable too!

Another big lesson learned was the art of “sucking rubber.” As we would approach a mega rapid (the
biggest one we faced had us going straight up a 15 foot wall of water) our guide would yell out for us to “suck rubber”, which was our cue to get low (low enough to suck rubber), hold on tight and brace for impact against the impending wall of water. The lower you got (the more rubber you sucked) the better the chances of the wave going over your head instead of hitting you in the chest and knocking you off of the raft. There are certain events in in your journey towards retirement that require a little bit of “sucking rubber” in order to make it through relatively unscathed. Sometimes you can see them coming from a mile away and prepare for them. Other times, having a guide that can tell you when to suck rubber can save your retirement account and keep it safely on the raft and heading in the right direction. Make sure you are paying enough attention to the economy and the financial indicators to know when a big rapid is coming. Or, make sure you have a financial guide who can see the rapids that you do not and give you your cue for when it's time to suck rubber.

The amount of beauty in the canyon was unbelievable. There were hidden waterfalls and oasis
around every corner - if you knew where to look. There were plenty of times our guide would pull up to a rock in the middle of a rapid, tie off ...and then head off towards what usually looked like nothing. But then we would duck around a rock wall or up a little canyon and find hidden swimming holes and lush gardens. I was amazed that, in the middle of the dessert, there was an amazing amount of water, flowers and trees IF you knew where to look. We would have passed them by, never having known they were there without our guide, who knew every nook and cranny of the river and exactly where to stop.

When it comes to investing for your retirement and making sure you have enough money at the end of the trip, getting there is kind of like traveling the 188 miles down the canyon. There will be some big rapids that you need to “suck rubber” through (like the crash of 2007) and there will be plenty of hidden waterfalls and oasis (great investment strategies) that you may not see if you’re traveling down a river you've never been on. People who use a guide are more prepared for their retirement, typically have more money in their retirement accounts and know how much they need to save in order to reach their retirement goals. There are a lot of reasons people try to handle their own retirement plans, but the bottom line is you’ll do much better if you have a little help. It’s never too late (or too early) to make sure you’re doing the right things for your retirement account, and it's always the right time to ask for a little help.

Stay tuned for part 2 - "The right equipment"

Tuesday, June 11, 2013

The Challenge Of Zombie Retirement Planning

I've been talking lately about "knowing your retirement number", that magic number or amount of money you'll need in order to retire (and stay retired) with the kind of lifestyle you'd like to maintain. It's important to know your number so that you know where you need to be (financially) when you get to retirement age. Knowing where you need to be allows you to create a road map to get there and it is one of the first steps in retirement planning. Everyone's number is different and is based on a lot of different factors. A few of which, as you'll see, make retirement planning pretty tough if you're a zombie!

Aside form the obvious challenges of working with zombies - they try to eat you at every
meeting, they don't answer your questions, they're constantly wandering off, etc - there are also a lot of planning challenges that come into play. For example, one of the biggest factors in your retirement number is longevity, or how long you expect to live after retirement. If, for example, you know you only have one year to live then you can spend every penny you've saved during that year without worrying about running out of money the next year. However, if you expect to live 30 years after retirement, your retirement number will need to be much bigger and you'll need to budget your spending because the money has to last much longer.

Hence the first problem of zombie retirement planning, in theory a zombie could go on existing forever! While the living can expect an average of 25 - 30 years of life after retirement, the walking dead may need to plan for double or triple that amount of years. Very few people have factored in their longevity and fewer still have saved enough money to live their pre-retirement lifestyle for 30 years. Imagine how difficult it is to convince a zombie to plan for 60 years!

Compounding the problem is the fact that life expectancy is only an average and about half of all the members of a certain age group will live past their life expectancy. So if your retirement plan is based on using up all of your income by the time you reach your average life expectancy, you have a 50 percent chance of outliving your income.

Second, life expectancy is not a constant, but rather a moving target. If you've reached 65 already, your life expectancy has already increased. After all, you've survived many people in your age group who died before you. Your new life expectancy based on your current age is called your longevity, and longevity is a more accurate assumption on which to base your retirement income planning.

Consider this: Americans who reached age 65 in 2011 are projected to live another 21 years to age 86, on average. If these same Americans reach age 86, their life expectancy would extend to age 93.

And here's one final thing to keep in mind: While a 60-year old man today has a 20 percent probability of reaching 95 and a 60-year-old woman has a 30 percent chance, there is a 40 percent chance that at least one member of a married couple at the same age will live until 95. Retiring couples need to carefully consider this when planning for retirement.

Making retirement income projections should involve balancing the risk of drawing down your income too quickly and being left with little to live on in your 80s or 90s, against spending your income too slowly and needlessly crimping your retirement standard of living.

It's natural not to want to consider your own mortality. Many workers planning for retirement, and even those on the cusp of retiring, see life after work as a golden time stretching into a hazy horizon. It can indeed be a wonderful second act, but that will depend on your taking an honest look at how far away that horizon really is.

You won't live forever. But you may live longer than you expect. Used correctly, life expectancy and longevity can be powerful planning tools that can help provide a truer picture of what you have to do to make your retirement years both comfortable and secure.

Fortunately if you're reading this, you're still among the living and don't have the extra challenges faced by the undead. Planning your retirement and thinking about your longevity may seem scarier than a night out with a crowd of walkers, but knowing your retirement number and working on a plan to get there can help put your mind at ease and insure the retirement of your dreams. If you don't yet know your number, you can access 3 great retirement calculators right now at https://pyz92550.infusionsoft.com/app/form/know-your-number. Or, for your very own personalized Retirement Income Replacement Analysis, email me at r.edgin@weinsurecolorado.com and request the Retirement Questionnaire. I'll email it to you at no charge.

Monday, February 4, 2013

Broken Legs, Skier's Liability, And Your Home Insurance Policy

Ski season is in full effect, and Colorado ski resorts are finally getting some much needed snow. My son and I decided to take advantage of the fresh powder and headed west, along with what seemed to be half of the residents of Colorado, for a day of fun in the snow. But unfortunately, I was involved in a very serious collision with a 6 year old boy that resulted in a broken leg and a trip to the hospital...for the little boy.

While skiing down an advanced run, I looked up the mountain to see if it was safe to make my way across. As I looked up, I saw Colton (named changed) coming at me at a very high rate of speed. Colton wasn't out of control, but he was going too fast and was not able to turn very well yet (which is why he was coming straight down the mountain). There was nowhere for me to go so I braced for impact and did my best to catch Colton as we collided in order to, hopefully, prevent serious injuries. Fortunately, Colton and I were both wearing helmets and, fortunately, I was able to wrap Colton up in my arms and fall in a way that put most of the impact on me. Unfortunately, Colton's leg landed under me and, as we slid down the slope, his leg was broken.

More than 55 million people per year hit the slopes in the United States, and every year, there are about 135,000 serious injuries and 40 deaths. What do you do if you find yourself tangled up with another skier who decides you were at fault for their injuries? Where can you turn to help you with legal and medical bills that you may be responsible for? You may be able to get some help from your home insurance!

Your home insurance policy includes medical payments to others and personal liability coverage which protects you and members of your family that are living with you for injuries to others that you may be responsible for, even if the injuries do not happen on your property! Your home insurance can help cover the costs of legal fees, medical bills, work loss and pain and suffering if you are liable for someone else's injuries in an accident.  There are some limitations, coverage does not extend to intentional acts, accicdents covered by auto (or other vehicle) insurance, or claims covered by worker's comp insurance. You are also bound by the limits on your individual policy and any exclusions that your insurance company may have listed, however, ski accidents are typically not excluded.

Make sure you carry high enough liability limits to protect your assets and future earnings. You don't want to find yourself at the wrong end of a lawsuit and have your insurance company tell you that there isn't enough coverage to pay for everything and the rest will be coming out of your pocket! Increase your medical coverage to $5,000 and your liability coverage to $500,000 to be on the safe side. If you do have to file a medical or liability claim, you will typically not be responsible for your deductible as deductibles don't apply to liability claims.

Hopefully, you never find yourself being sued or facing a situation where you are responsible for someone else's injuries. Luckily, I wasn't injured in my ski collision. Colton ran into me and suffered a broken leg, but things could have been much, much worse. If you're going skiing, play it safe and make sure you follow the National Ski Patrol's skier code of conduct.

  • Always stay in control, and be able to stop or avoid other people or objects.
  • People ahead of you have the right of way. It is your responsibility to avoid them.
  • You must not stop where you obstruct a trail, or are not visible from above.
  • Whenever starting downhill or merging into a trail, look uphill and yield to others.
  • Always use devices to help prevent runaway equipment.
  • Observe all posted signs and warnings.
  • Keep off closed trails and out of closed areas.
  • Prior to using any lift, you must have the knowledge and ability to load, ride and unload safely. 

Wednesday, December 19, 2012

Insurance And The End Of The World

As I'm writing this, the end of the world is just a few days away...IF you believe the Mayan calendar. And IF you're like most folks out there, I'm sure you're asking the rather obvious question on most people's minds, "will my insurance cover my cars and house if they're destroyed by the end of the world"? You may also be concerned that your life insurance wont' pay a death benefit if you don't make it through the end of the world events. Here are a few things to put your mind at ease when it comes to your insurance:

  1. Most insurance policies specifically list things that are excluded from coverage and the list can be easily found in every policy that you buy. Check you policy and you'll most likely find that the end of the world is NOT listed as an exclusion of coverage. I know what you may be thinking, it's the stuff leading up to the end of the world that you'll need to have coverage for, such as meteors, sun flares and super volcanoes that erupt in Yellowstone National Park. Don't worry, you probably won't find any of those disasters listed as an exclusion either.
  2. Even things that ARE excluded can still be protected if you're willing to spend a few extra dollars. Earthquakes and floods, two real possibilities for the upcoming doomsday, are typically not covered by home insurance policies. However, you can usually add an earthquake endorsement to your home insurance and buy flood insurance through the National Flood Service.
  3. If your neighbor also survives the apocalypse but then breaks into your house to steal your survival gear, your insurance company will replace it under your policy. If they steal your 4x4 in order to get to higher ground, that's covered to as long as you carry comprehensive coverage. Insurance companies don't ask why something was stolen or refuse to replace the item just because the theft had to do with the end of the world.
  4. If a zombie attack makes your home unliveable, your home insurance should have coverage for "additional living expenses" that will pay to put you up in a zombie free hotel until your home can be repaired. Most home insurance policies cover vandalism, even if caused by the walking dead.
  5. If your house isn't damaged but an EMP blast has knocked out power to 1/2 the continent, don't worry about the hundreds of pounds of food you've placed in the freezer in preparation. Most home insurance policies have coverage for loss of power resulting in food spoiling. Simply eat your freeze dried food and the fruit from your sustainable garden until power is restored. Then, call your insurance company and file your claim. Your home insurance should provide you with the needed money to restock the freezer in you underground bunker (minus your deductible).
  6. If you purchase the right type of life insurance (non accidental death), about the only two types of death that may forfeit the payment to your family are suicide (within the first year or two, depending on the state you live in) and fraud. If it's pestilence, being swallowed hole by the ground beneath you, a falling asteroid or even a falling plane that was hit by a falling asteroid, your policy will pay your beneficiary the death benefit so they'll have plenty of money to stock the underground bunker they plan on living in.
The chances of the end of the world taking out your home or car may be increasing, but there's not much need to worry about your insurance policy not covering the damage. And if that doesn't help put your mind at ease, you can always forget your car and house and settle for living on the personal ark you built for your family in preparation for the floods.

Monday, October 22, 2012

Home Insurance Guest Medical Coverage

I'm writing this during the spooky season of zombies, ghosts and goblins - Halloween. But, there is something even scarier out there than Jason, Freddy and Michael Meyers combined...paying for your guests medical bills!

What happens if your Friday night pumpkin carving party turns into "Attack Of The Kitchen Knife" and one of your guests has to make a visit to the emergency room? Who is responsible for the bills your guest incurs from things that go bump in the night? The answer is, it depends! Every situation is different and I cannot tell you which will result in your being responsible and which will not, but if it turns out you DO have to pay for the medical needs of a guest, where is the money going to come from?

Hopefully (if you've got the right kind of home insurance coverage), it will come from your home insurance policy. Most home insurance policies have Coverage F - Guest Medical Coverage. The limit of coverage you choose is up to you and typically ranges from $1000-$5000 in coverage. Meaning if your guest is injured on your property your home insurance would pay the first $1000-$5000 of guest medical bills, depending on what limit you chose for your policy. Here is how a typical insurance policy explains guest medical coverage:


"COVERAGE F – MEDICAL PAYMENTS TO OTHERS
We will pay the necessary medical expenses incurred or medically ascertained within three years from the date of an accident causing bodily injury. Medical expenses mean reasonable charges for medical, surgical, x-ray, dental, ambulance, hospital, professional nursing, prosthetic devices, and funeral services.


This coverage does not apply to you or regular residents of your household other than residence employees. As to others, this coverage applies only:
1. to a person on the insured location with the permission of any insured; or
2. to a person off the insured location, if the bodily injury:
a. arises out of a condition in the insured location or the ways immediately
adjoining;

b. is caused by the activities of any insured;
c. is caused by a residence employee in the course of the residence employee's employment by any insured;
d. is caused by an animal owned by or in the care of any insured."

What happens if you do NOT have guest medical coverage, or if you do not have enough coverage? Here's the scary part, you still owe the money! Your insurance policy does not assume responsibility and liability for you, it simply pays the amount you owe, up to the policy limit, and then stops paying. That is why I recommend increasing your guest medical coverage to the maximum offered under your home insurance policy. The price is minimal for the extra coverage.

Keep in mind, you could have some additional coverage (emphasis on could) for guest medical under your liability limit, but do yourself and your family a favor and remove as much of the scary stuff as possible. Increase your Coverage F - Guest Medical Coverage to the max allowed. It should only cost you a couple of extra dollars a month and it's money well spent.


Thursday, August 30, 2012

Lessons Learned - Medical Power Of Attorney and Living Will

If we've talked lately, you already know that my dad spent a week in the hospital last month. Fortunately, he's getting back to normal and recovering nicely from 2 scary heart attacks, but the time he spent in the hospital taught me a few lessons that I needed to learn for my own family. I had not considered - and did not have - a Medical Power of Attorney or a Living Will set up for wither myself or my wife. Both are free, easy and take effect as soon as they are filled out, signed and witnessed by a 3rd party. I learned how important they are and now have it all taken care of. Here are a few things you should know:

1. Medical Durable Power Of Attorney: A Medical Durable Power Of Attorney (MDPOA) is a document you sign naming someone to make your healthcare decisions if and when you are not able to. The person you name is called your healthcare agent. Your MDPOA can become effective immediately, or you can make it become effective only when you are unable to make your own medical decisions.

You can appoint anyone to become your healthcare agent as long as that person is at least 18 years old, mentally competent, and willing to be your agent.Your agent should also be someone who can confidently deal with lots of healthcare providers over what could be a long time. It is preferable to pick an agent who lives in the same state or even city as you do,and it's also a good idea to appoint one or two back-up agents, in case your first choice is not available or able to serve.

Your healthcare agent has all the powers of decision making you do: He or she can consult with healthcare providers, review or get copies of your medical records, and make all necessary healthcare treatment and placement decisions. The agent must act according to his or her understanding of what your wishes and preferences would be. He or she must set aside his or her own values and preferences and do what you would do.

You may put instructions into your MDPOA document to help guide your agent and your healthcare providers so they are better aligned with your wishes. A MDPOA can be printed by clicking here: Printable MDPOA

2. Living Will: A living will is a document you sign telling your doctors to stop or not start life-sustaining treatments if you are in a terminal condition and can't make your own decisions or if you are in a persistent vegetative state (PVS). A terminal condition is one that is incurable or irreversible and for which life-sustaining treatment will only postpone the moment of death. PVS results from a severe brain injury and generally means that the person is alive and may appear to sleep and wake, but is completely unaware of his or her surroundings; cannot speak, drink or eat; and may not be able to feel or react to pain.

A living will only goes into effect 48 hours after two doctors certify that you are in a terminal condition and can't make your own decisions or you are in PVS. Your doctors must make a good effort to notify persona close to you that this certification has been made and they will withdraw or withhold life-sustaining treatment within two days. You can include a list of persons to be notified in the living will document, with their contact information. You can also include a list of persons authorized to talk to your doctors about your condition and care. These persons are not authorized to make any decisions about your care.

In Colorado, you may also designate in your living will that your doctors should stop or not start any tube feeding and other forms of artificial nutrition and hydration, once the terminal or PVS certification has been made, unless they consider it necessary to provide comfort or relieve pain. You may also include other instructions about your care, but these instructions will only go into effect at the same time as your living will. You can print a Living Will by clicking here: Printable Living Will

No one likes to think about these types of things happening to them, but it is better for you to give it a little thought now while you can clearly state what you would like to happen instead of leaving it up to your family who may not know what your wishes really are. They will already be dealing with a lot of stress, there's no reason you can't make things easier on your family by taking 10 minutes to fill out your MDPOA and Living Will today!

Wednesday, August 29, 2012

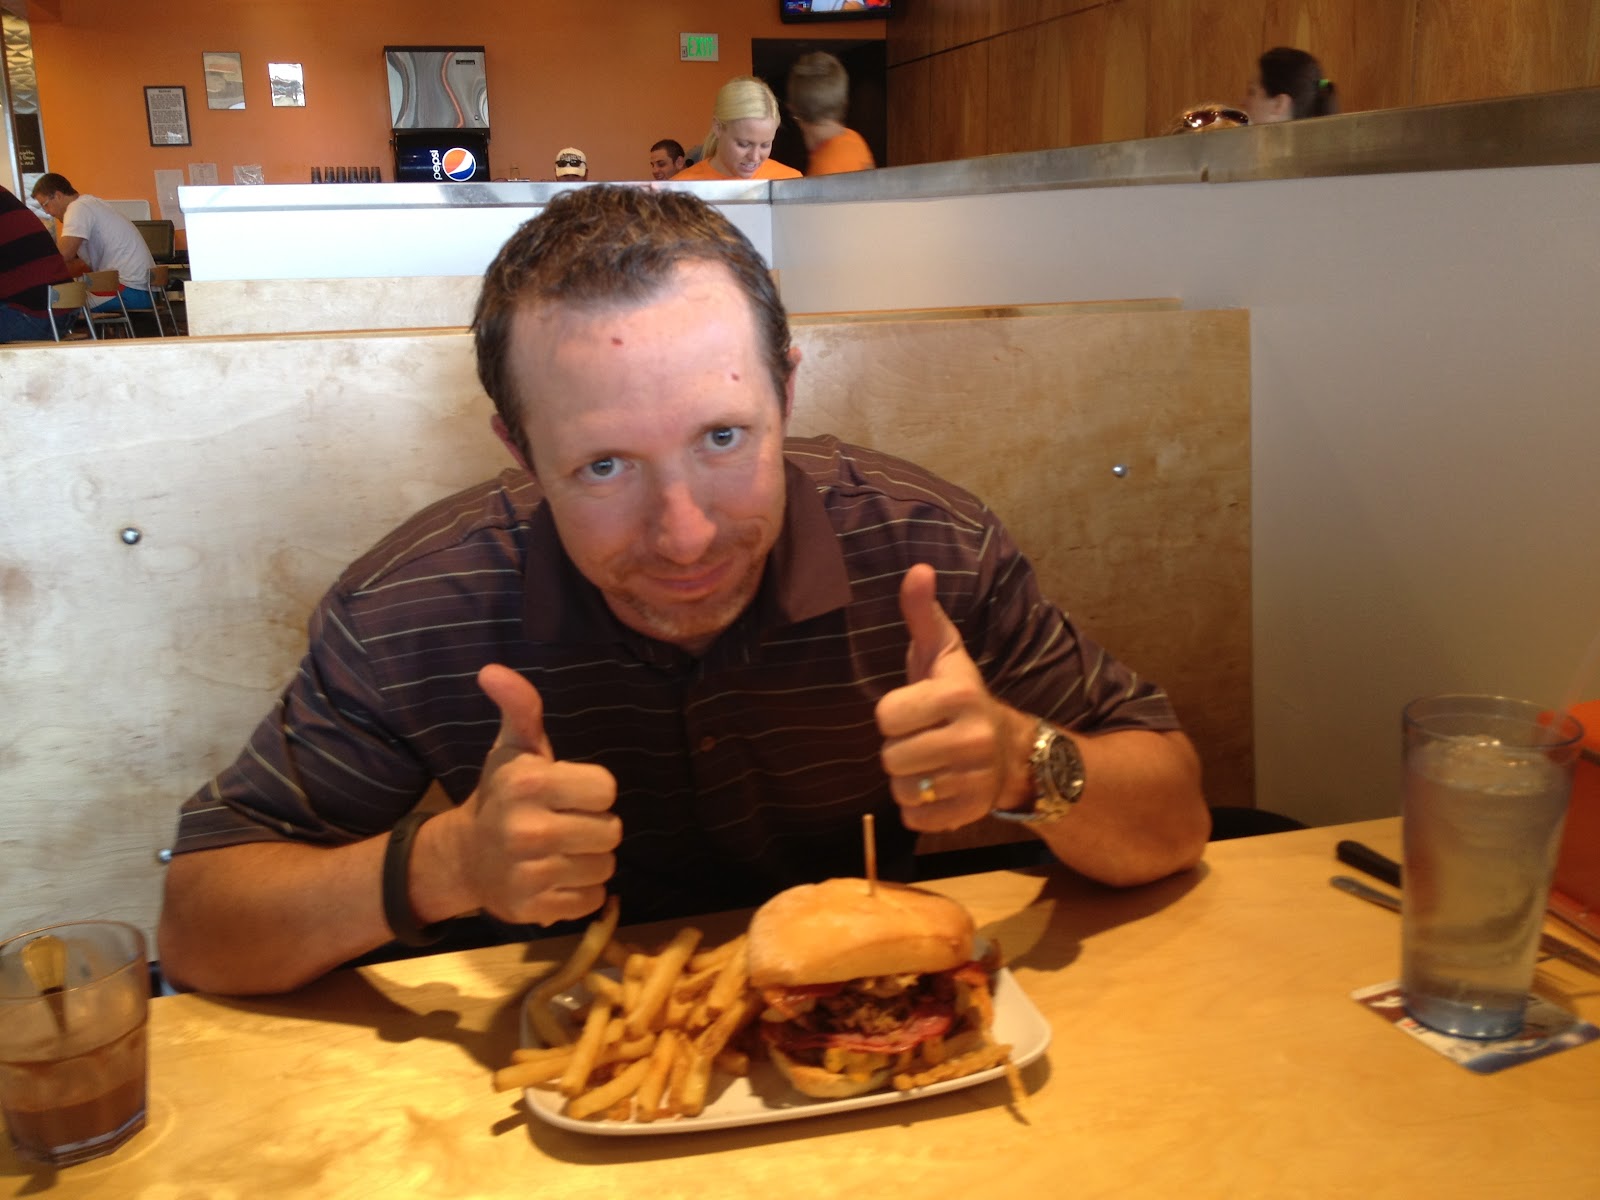
A Review: Crave Burger

 What does a "3 Little Pigs" burger from Crave Burgers have to do with insurance? Absolutely  nothing! But, since I've been focuing on "A Taste Of Colorado" throughout the year and giving away gift cards to Colorado based restaurants, it seemed like a good excuse to indulge in one of my favorite guilty pleasures, a cheeseburger!

However, calling the "3 Little Pigs" a cheeseburger is kind of like saying the Mona Lisa is "just a painting." As far as cheeseburgers go, this is more of a masterpiece! For starters, it's made from scratch when I order so it was super fresh. Not only is it fresh, I can tell by looking at my burger that the ingredients are all top quality.

Speaking of the ingredients, as the name implies the "3 Little Pigs" burger is topped with 3 different, yet equally delicious, types of pork. PLUS, they piled a mound of onion strings in top too (my mouth is watering again just writing about it!). Even the bun was awesome.

The burger itself is bigger than my mouth , super juicy and super tasty. My plan was to cut it in 1/2 and save the other 1/2 for dinner but I wasn't ready to quit eating after I made it through the first 1/2 so I ended up eating the whole thing. I will, however, be skipping dinner!

I also had some home cut fries and a wonderful chocolate shake (I'm glad I don't eat like this every day!) with my meal. By the time I was done, I could hardly move, but I was very satisfied. Crave's burgers are all unique, they're all gigantic and they're all delicious. I've tried 3 of their masterpieces so far and I'm already looking forward to my next adventure in burgers. If you're not really the burger type, they've also got sandwiches and salads on the menu for you.

If you'd like to give Crave Burgers a try, make sure you introduce some of your friends and family to our office first. We'll reward you with a Crave gift card so you can go check out one of their amazing burgers on us!

Tuesday, July 3, 2012

Home Inventory - Do You Know What You Own?

It sounds like a pretty easy question which should have an easy "yes" for an answer, but reports show that people who have a total loss at their home (ie. a fire) often find that they are unable to replace everything they own. The problems, they either cannot remember everything they have or they do not have everything properly covered, can both be solved with a simple home inventory and an annual review with their insurance agent. Here is what the Rocky Mountain Insurance Information Association has to say about home inventories:

"Before a catastrophe strikes and you're faced with a loss, make a home inventory - lists, pictures or a videotape of the contents of your home. After all, would you be able to remember all the possessions you've accumulated over the years if they were destroyed by a fire? Having an up-to-date home inventory will help you get your insurance claim settled faster, verify losses for your income tax return and help you purchase the correct amount of insurance.
                        
According to a 2012 survey from the National Association of Insurance Commissioners (NAIC), more than half of Americans don't have a home inventory of their possessions, putting them at risk for inadequate home insurance coverage, should severe weather strike.
  • Survey results show 59 percent of consumers have not made a list or inventory of their possessions. Of those individuals with a home inventory, 48 percent do not have receipts; 27 percent do not have photos of their property; and 28 percent do not have a back-up copy of the inventory outside the home.
  • Additionally, 59 percent of people with inventories have not updated their inventories in more than a year, meaning new purchases and gifts may not be covered.
Taking Inventory
Start by making a list of your possessions, describing each item and noting where you bought it and its make and model. Clip to your list any sales receipts, purchase contracts, and appraisals.
  • For clothing, count the items you own by category pants, coats, shoes, for example - making notes about those that are especially valuable.
  • For major appliances and electronic equipment, record their serial numbers usually found on the back or bottom.
Don't be overwhelmed! If you are just setting up a household, starting an inventory list can be relatively simple. If you've been living in the same house for many years, however, the task of creating a list can be daunting. Still, it's better to have an incomplete inventory than nothing at all. Start with recent purchases and then try to remember what you can about older possessions.
Big ticket items: Valuable items like jewelry, art work and collectibles may have increased in value since you received them. Check with your agent to make sure that you have adequate insurance for these items. They may need to be insured separately.
Take a picture: Besides the list, you can take pictures of rooms and important individual items. On the back of the photos note what is shown, where you bought each item, and the make. Don't forget things that are in closets or drawers.
Videotape it: Walk through your house or apartment videotaping and describing the contents. Or, do the same thing using a tape recorder.
Use a personal computer: Use your PC to make your inventory list. Personal finance software packages often include a homeowners room-by-room inventory program.
Storing the list, photos and tapes: Regardless of how you do it (written list, floppy disk, photos, videotape or audio tape), keep your inventory along with receipts in your safe deposit box or at a friend's or relative's home. That way you'll be sure to have something to give your insurance representative if your home is damaged. When you make a significant purchase, add the information to your inventory while the details are fresh in your mind."

To download a home inventory that can be printed and filled out, click here: HOME INVENTORY.
You can also use a FREE online tool from the Insurance Information Institute that will allow you to create a free account and use an online inventory OR download the app for your phone and take pictures of your stuff and attach it to your inventory. You can access the tool by clicking here: Know Your Stuff

If you're going to pay for insurance, you may as well make sure it does what it is intended to do, make you whole after a loss by replacing or repairing your property that is damaged or destroyed. One of the best ways to make sure that happens is by having a home inventory and meeting with your insurance agent every 12-24 months for a quick coverage review. If you've not reviewed your policy in a while, even if we are not the company you use, please make an apointment with us today so we can make sure you'd be okay - financially - if your home was destroyed. Call us at 685-8585 for a Professional Insurance Review.

Tuesday, June 26, 2012

Wildfire And Your Home Insurance, Important Things To Know

With a large number of wildfires burning throughout the state and a number of my clients under a mandatory evacuation of their homes, this seems like a good time to share a few pieces of information about your home insurance in regards to wildfires. As I'm writing this, the entire north-east side of Colorado Springs is covered in smoke from the Waldo Canyon fire. If you find that the fire is moving in your direction or your ordered to evacuate your home, here are some things you should know (and do):
  1. Home Inventory: There's no time like the present to update your home inventory. Although many insurance companies do not REQUIRE a home inventory, it is very wise to document what personal property you have in your home. You can run a vide camera through each room, take pictures or fill out a home inventory record (print one here: https://docs.google.com/open?id=0B3jkfR37iTC3ZDZhMjA0YzYtNzA1OS00NWIwLWExZmQtOTdiZGU5NTNmZmZi ). Whichever method you choose, keep it somewhere off primses. Preferably, send it to your insurance agent and have them store it at their office.
  2. Mandatory Evacuations: Most insurance companies WILL cover the expenses incurred from a mandatory evacuation, such as hotel and food costs. However, you must reach your deductible first. If you have a $1000 deductible and you incur $800 worth of addidtional living expenses, you would most likely not be reimbursed by your insurance company because the amount is below your deductible (your deductible is the amount of the claim you are required to pay). Keep all of your receipts for your extra living expenses in case you need to file a claim. If you get home and find you have other damages, such as smoke damage, it would be added into the same claim and be covered under the same deductible.
  3. It Is Probably Too Late To Change Your Coverage: Once a neighborhood has a wildfire moving in it's direction, it is most likely too late to make any changes to your home insurance. Raising coverage, lowering deductibles and adding special items such as art or jewelry is usually prohibitted by the insurance company after a wildfire has been declared in the area. Presently in Colorado Springs, most insurance companies have issued a non-bind order for any property west of I-25, meaning there are no increases in coverage allowed and no new home insurance policies can be written until the non-bind status is removed. My advice, review your coverage with your agent BEFORE your area is affected! An insurance checkup should be done every 12-24 months to make sure your coverage is set up properly.
Hopefully the Waldo Canyon fire here in Colorado Springs and the rest of the wildfires burning across the state of Colorado will be brought under control soon with minimal loss to property and no loss of life. Hopefully, you will never find yourself in a mandatory evacutaion situation. Just keep in mind that if you are facing an evacuation or damage to your property, you do have help available from your home insurance company.

Good luck to all of the fire fighters out there and thank you for your hard work and efforts to keep us safe.

Sunday, June 24, 2012

Be Prepared For Emergency Evacuations

I've just spent about 2 hours watching the most recent forest fire to hit Colorado spread at a very rapid pace. Forest fires are always a scary thing, but this one  - right at the edge of Colorado Springs and threatening many, many homes - really drives home how important it is to be fire safe and evacuation ready if you live anywhere near a wildfire or high-tree area.

The pictures I'm using for this post were taken by my wife and I, from my driveway and areas right around my home. Fortunately no homes have burned so far, but with mandatory evacuations taking place across the front range, our city is getting first-hand experience of just how dangerous and fast-moving a wildfire can be.
The first thing to do is make sure you're signed up for emergency notifications with your local 911.  Registering your cell phone for emergency notifications will help insure you get the message if you need to evacuate your home and head towards a safer area. In El Paso and Teller counties, you can register your phone at http://www.elpasoteller911.org/.
If you do receive the call (or just feel it's the prudent thing to do) to evacuate your home, here are some important tips and things to remember to keep your family safe:
  1. Know how you are going to get out: The first step is to make sure everyone in your family knows the escape route from your home as well as your neighborhood. If you have a home fire, everyone should know the quickest way to get out of your home, and if your neighborhood has a disaster, everyone should know the best way to leave the area. Take the time to practice, as a family, your escape route and have a backup route in case your first way out is blocked.
  2. Know what you are going to take: Have an evacuation preparedness bag ready for everyone in your family. Keep a few days worth of clothes and medications inside so you don't forget them if you are in a hurry. Have a gallon of water for each person as well as a bit of non-perishable food ready in case it takes a longer amount of time to get to a safe area. Know where your important financial and family documents are and be ready to gather them up if needed. If time allows and you are wondering which items from your home you should take, start with things that are irreplaceable. Your insurance policy will help you replace your TV if it is destroyed, but your old photo albums, baby books and mementos are a completely different story.
  3. Know what you will do with your pets: Make sure your pets are ready for travel as well. Have a few days worth of pet food ready to go and have a plan for pet shelter in place in case your pet or animal is unable to stay with you.
  4. Know where you are going to meet: If your family is not together when an evacuation happens, everyone should know where they will be meeting, and it should be somewhere that is a safe distance from your home. If local phone service were interrupted or cell phones were down, you may not be able to reach everyone in your family at the time of an evacuation.
  5. Know when it's safe to go back: Stay informed with local authorities to know what is happening in your area. Phones, TV and power may all go out in an emergency, so keep a hand-held radio with your emergency kit. If your radio is battery powered, keep an extra set of batteries on hand as well.
Natural - or man made - disasters can happen at any time. Being alert and prepared to deal with an emergency will help keep your family safe and protected. Have the conversation about emergencies with everyone in your family as soon as possible (before an emergency happens) and practice dealing with an emergency 1-2 times per year. Evacuations can be scary for kids but if you practice and prepare for what to do they'll handle things much better if a real emergency were to occur.

For a complete list of items to keep in your evacuation bag and other tips on emergency preparedness, visit the Red Cross emergency preparation page at http://www.redcross.org/www-files/Documents/pdf/Preparedness/checklists/Be_Red_Cross_Ready.pdf

Tuesday, June 19, 2012

Dealing With The Insurance Company When Your Car Is A Total Loss

My daughter recently crashed her 2002 GMC Envoy, damaging the left door, front left quarter panel and front bumper. I thought the damage would be repairable (which it is), but the insurance company decided to total the car instead of repairing it. As you can see from the picture, the car does not look totaled. The estimate for the repairs came in at about about $6000.  The truck is worth about $9,500, so why would the insurance company choose to total it instead of repairing the damage? I'll answer that question and give you a few tips if you find yourself working with a claims department on a vehicle they consider a total loss.

Why would they total the car if it's cheaper to repair it? Insurance companies always choose the route that will cost the company the least amount of money. If a car needs repairs reaching 65% or more of the vehicles total value, it is often times less expensive to actually total the car instead of repairing it. The reason for this is the salvage value of the car. Once an insurance company pays you for the loss of your car, they turn around and sell it for it's salvage value, recouping a portion of the amount they paid you. When you subtract the salvage value from the amount paid out, it is often times less expensive than actually repairing the car. For example, if the salvage value on my daughter's Envoy is $3,500, the insurance company's cost is back down to $6,000. Then add in other factors like storage costs of a car before and after repair, rental car costs during repair and the possibility of finding more damage once a car is torn apart and you can see how they can save money by actually totalling a car instead of repairing it.

Tips for dealing with a totaled car: If you do find yourself in the unfortunate situation of a totaled car, there are some things to remember that will help you get the most accurate payout from your insurance company. Chances are you won't like the first offer made to you for your car, so it's your job to help the insurance company give you the right amount. Here's how:
  1. You're in this together: Remember that the claims adjuster you're dealing with is human, and wants to be treated as such. Lots of people forget that the claims adjuster is on your side and they really do want to be fair with you. It's not you against the insurance company and the claims adjuster is not looking to cheat you. Kindness and common courtesy can go a long way! Your claims rep is probably dealing with a hundred or so claims in addition to yours. They've got a lot of work to do and they probably have a lot of people yelling at them. It's a stressful job and they really appreciate dealing with clients who show a little patience and understanding.
  2. Do your homework: These days, insurance companies don't just look at the book value of your vehicle. In fact, the book value is one of the lesser considerations when determining what your car is worth. Claims adjusters will be shopping online for a car just like yours to see what you could buy it for today. Make yourself a log of every car for sale within 75 miles that matches your vehicle. Check on Ebay, Craig's List, Autotrader, Kelly Blue Book and maybe even the local classifieds. Keep track of which site each car came from, the price and mileage of the car, the model (in case it is different than your's) and any differences that would make your car worth more or less. This may sound like a lot of work, but it should take you no more than an hour, and that hour will probably put some extra money in your pocket! When I was researching 2002 GMC Envoy's to replace my daughter's, I found 11 within a 75 mile radius.
    1. Make sure the adjuster is using the right information: Claims reps have a lot of work to do and they may forget to add in features that your vehicle has, or they may pick the wrong model all together. They're not doing it on purpose, but they are working fast and they are not as familiar with your car as you are. Make sure you tell them about any thing they may have overlooked, like a sun roof, 6 disc changer, power seats, etc. My claim adjuster picked the wrong model of Envoy and the original estimate for my payoff was $2000 less than the final amount.
  3. Don't forget the extras: If you've recently replaced the tires, gotten a tune up or an oil change or done other service work to the car, make sure your claims rep knows about and takes it into consideration. The same is true of any extras you've added to the car like after market rims or stereo systems (some insurance companies require that you add in the extras to your policy in order for the to be covered. Check with your local agent for the specifics on your policy).
  4. It's okay to negotiate: The first offer they bring you may not make sense to you, but there's no reason you have to accept it right away. The claims adjuster will break down the offer and give you a detailed explanation of how they came up with the amount your vehicle is worth. If it doesn't sound right (or fair), let them know you'd like to take a day and research things a little bit. Let them know that you appreciate their work but things sound a little low. You're not required to accept the offer they make you, but keep in mind, if you cannot reach an agreement you will most likely have to go to mediation.
  5. You can still keep the car: If you decide that the damage causing your car to be a total loss is just cosmetic and you'd like to keep the car (or even if it's not cosmetic but you'd like to keep the car and repair the damage yourself) the insurance company will allow it. There have been plenty of hail storms here in Colorado lately that leave a car pitted, but otherwise in perfect driving condition. If you don't mind the hail dings, just let the insurance company know you'd like to keep the car. They'll adjust their offer to you by subtracting out the salvage value (the money they would get for selling the car to a salvage yard) and pay you the rest. Keep in mind, the car will not be allowed to have comprehensive and collision coverage because it has already been deemed a total loss, but you can still keep it insured and drive it for as long as you'd like!
It's never fun dealing with an insurance claim, but it doesn't have to be a bad experience either. Remember the positives, hopefully no one was seriously hurt in the accident (the most important thing) and you've got an insurance company working with you to help get you back to where you were before the accident. Yes, there will be some out of pocket expenses, like your deductible, but it's a whole lot better than if you had no insurance at all. Keep a good attitude and you'll be back on the road before you know it.

Robert Edgin


Thursday, May 17, 2012

Colorado Hail Season Is About To Begin!

It's that time of year again - hail season - the scariest time of year for Colorado insurance companies. Hail storms are unpredictable, devastatingly expensive and, unfortunately, way too common of an event here in southern Colorado. Read the article below from the Rocky Mountain Insurance Information Association and it'll be pretty easy to see why home insurance rates have been on the rise throughout the state:

The largest recorded hailstone in U.S. history fell on July 23, 2010 in Vivian, South Dakota, measuring
8 inches in diameter and weighing 1.94 pounds. The prized stone is now on ice at the National
Center of Atmospheric Research in Boulder, Colorado. The previous record hailstone fell in
Aurora, Nebraska on June 22, 2003 and measured 7 inches in diameter and weighed 1.67 pounds
(NOAA).

Colorado Hail Statistics

Colorado’s damaging hail season is considered to be from mid-April to mid-August. Colorado’s
Front Range is located in the heart of "Hail Alley," which receives the highest frequency of large
hail in North America and most of the world, so residents usually can count on three or four catastrophic (defined as at least $25 million in insured damage) hailstorms every year. In the last 10 years, hailstorms have caused more than $3 billion in insured damage in Colorado. As a result, up to one-half of your homeowners insurance premium may be going toward hail and wind damage costs. If you carry comprehensive coverage on your auto policy, hail damage is covered by almost all insurance companies. Comprehensive insurance is optional, but if you live in a hail prone area, the insurance industry recommends this coverage.

Colorado's Most Costly Hail Storms

With the exception of the May 22, 2008 Windsor tornado and the hailstorm that hit Pueblo on July 29, 2009, Colorado’s ten most costly hailstorms were centered in the Denver Metro area (which makes sense, because that’s where the largest concentration of property in the state is located).


What To Do After A Hail Storm

First, if a hailstorm strikes, don’t go out in the storm to try to protect your
property. You could be injured.
Download RMIIA's "Hail Damage Fraud" brochure.

Assess the damage.
  • Check trees, shrubs and plants around your house. If they are stripped
    of their foliage, there is a possibility that your roof is damaged. You
    should also check for roof damage if patio covers, screens or soft
    aluminum roof vents are dented.
  • Check your car for dents and broken or cracked glass.
Protect your property from further damage.
  • If you find signs that hail has battered your property, take immediate steps to protect it from further damage.
  • Cover any broken windows and holes in your roof so that no water can enter and damage your home’s interior.
  • Cover any broken glass in your car to prevent damage to the interior from rain and remove glass from the car’s interior to prevent cuts in upholstery and carpet.
File your claim
  • Call your agent or company as soon as you notice damage. Practically all homeowners policies cover hail damage. You car will be covered if you’ve purchased comprehensive coverage.
  • If your agent or company requests you to do so, follow up your call with a written explanation of what happened.
  • Save receipts for what you spend and submit them to your insurance company for reimbursement.
Select a repair company.
  • After an insurance adjuster has surveyed the hail damage to your property, select a reputable roofing company or auto body shop to make repairs.
  • Allow only the insurance adjuster and roofer you have selected to get up on your roof. Each time someone walks on it, more damage can occur.
  • Be wary of out-of-town roofers who move into an area and set up shop following a storm. While most of these firms are reputable, some have collected money from homeowners and moved on to the next storm site without paying suppliers or leaving work unfinished. This can leave homeowners holding the bag for those additional costs. It’s a good idea to select a company with established credibility and local references. Word of mouth is still your best guide.
  • Be sure roofers have workers compensation and liability insurance. If they don’t, you may be held liable if one of the workers is injured or if they damage a neighbor’s property.
  • Don’t make final payment to the roofing company until your roof has been inspected and you are satisfied.
Use hail resistive roofing materials.
  • When building a new home or replacing your roof consider using hail-resistive roofing products. The insurance industry has an Underwriters Laboratory standard ranking, the UL 2218 standard. The standard has four impact-level designations that will help you compare products. Roof coverings that show the most resistance earn a Class 4 rating; the least, a Class 1 rating.
  • Impact-resistant Roofs: Smart Steps to Reduce Hailstorm Damage is a free, online learning experience that consists of four self-paced learning modules. It teaches homeowners and other consumers about the benefits of installing impact-resistant residential roofing products. Click here for more information.

Sunday, February 26, 2012

Your Home's 3 Values

Are you selling it, paying taxes on it or insuring it? The answer will determine which one of your home's 3 values you should be using. You want one to be high, one to be low and one to be very, very accurate in case you ever need to use it. Let's look at the different values and what they mean for your home.
  1. Real Estate Value: This is the value that your home would sell for. Unless you're planning on selling your home (or trying to refinance), this value is irrelevant. You obviously want this value to be as high as possible but you really only need to know this value a few times during your home ownership.
  2. Assessor Value: This is the value your taxing entity places on your home and determines how much property tax you will pay each year. Most counties use their own formulas for determining the value of your home (plus any attached/detached structures) and then send you an annual tax bill according to the appreciation or depreciation of the value compared to the previous year.
  3. Insurance Value: The insurance value determines how much it would cost to rebuild if your home was totally destroyed. It is very important to make sure you review the value that your insurance company has placed on your home. You don't want it to be higher than necessary, which will cost you more in your annual premiums. However you don't want it to be lower than needed to completely replace your home. Statistics show that 60% of homes are underinsured, meaning they would not have enough insurance to completely rebuild if they were destroyed. Although the insurance value does not include the land, it is often higher than the real estate value (especially in the current environment) for a number of reasons:
    1. There is more involved with RE-building than with building from scratch. In most cases it actually costs more to rebuild than to build.
    2. You have to tear it down first! In order to start re-building you must first remove the remaining debris from the home. This is a very expensive task and can cost upwards of $25,000 or more.
    3. Building codes with the city, state and county can - and do - change, adding extra costs to the rebuild.
    4. Material and labor are constantly changing, and usually not in the same direction as the real estate market. For example, last year the price of concrete went up 5 times due to a shortage caused by the chineese buying all of the US concrete for building projects in China.
While all 3 home values are important, only one will make sure your home is completely rebuilt if it were destroyed. Knowing each and making sure the insurance value is accurate is something that should be reviewed and kept up to date every 12-24 months. If you make any changes to your home, such as remodelling or adding rooms, make sure you meet with your agent to update the information about your home. It could mean the difference between rebuilding the home of your dreams or getting stuck with an incomplete home because you run out of insurance money!